
First-time buyers
Your first set of keys, explained step by step—low-down-payment options and down payment assistance programs for eligible buyers.
Rick Anthony · 320+ loans closed · Eight states
Financing as considered as the home itself.
Your first home, your forever home, your next investment — each deserves a strategy, not just a rate. One loan officer, from the first conversation to the keys.
Complimentary consultations · Apply online · Free first-time buyer class
Successful loans closed
In closed loan volume
States licensed · West to Southeast
Loan programs, from FHA to jumbo
Where I lend
Licensed from the Pacific Northwest to the Carolinas. Relocating, buying a second home or investing out of state? One loan officer can follow you there.
Two ways in

Low down payment options, down payment assistance and a step-by-step plan — so buying your first home feels exciting, not overwhelming.
Explore first-time buyer options
Jumbo, interest-only, asset-based and business-owner financing, structured with discretion and placed across a wide lender network.
Explore luxury & investor financingWho I work with
Every client receives the same standard of care—whether you're buying your first home with down payment assistance or structuring financing around a business, a portfolio or several properties.
Your first set of keys, explained step by step—low-down-payment options and down payment assistance programs for eligible buyers.
Write-offs can make strong income look modest on paper. Bank statement and profit-and-loss programs may document what you actually earn.
Bonuses, commissions and variable compensation, reviewed carefully so the full picture of your income is presented well.
From a first rental to a growing portfolio—DSCR, bridge and equity strategies built around cash flow and your next acquisition.
Jumbo financing for primary residences, second homes and custom builds, including options for clients whose wealth is primarily in assets.
VA purchase loans and the VA IRRRL streamline refinance for eligible service members and veterans, plus a smooth plan when you're moving between any of the eight states I serve.
Financing, thoughtfully structured
With Barrett Financial Group I'm not limited to one bank's products. I take your scenario to a wide lender network and place it where it fits best.
Not sure where your scenario fits? That's what a private consultation is for.
Program availability and qualification vary by lender, property, occupancy and state. All loans are subject to underwriting and approval.
Not sure which program fits? Ten minutes on the phone usually answers it.
Free first-time buyer class
A free, live online class for first-time buyers. In about an hour you'll learn how the process works from pre-approval to keys — and leave with a clear next step.
Educational only. Not a loan offer or commitment to lend. Specific advice is limited to states where Rick is licensed.
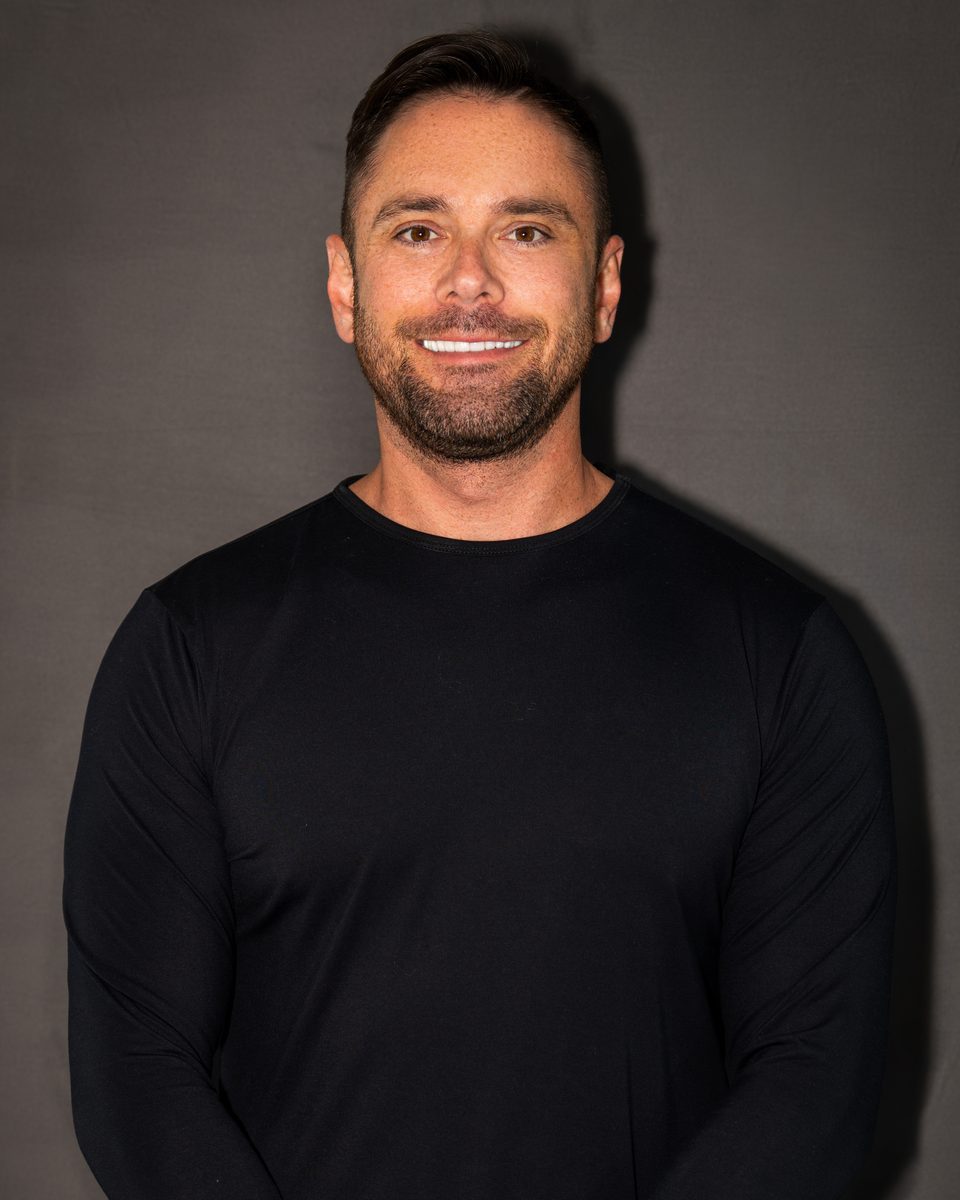
A great home loan should feel effortless.
The Rich Lends experience
Hi, I'm Rick.
After more than 320 successful closings and over $138.5 million in loans, I know a home loan deserves more than a rate quote. I take the time to understand where you are today and where you want to be — then build the loan around that plan.
As a loan originator with Barrett Financial Group, I can compare options across a wide lender network instead of one bank's menu: first-time buyer and down payment assistance programs, conventional, FHA and VA, jumbo, self-employed and investor financing — in eight states.
The moment that matters
The hard part is everything before them. That's my job — so closing day is simply a celebration.
Start your secure application
The process
A clear plan at the start means fewer surprises in underwriting and a smoother path to closing.
Your goals, timeline, properties and how your income and assets are held.
We compare suitable programs, down payment, reserves and fixed, adjustable or interest-only options.
I stay on your file through appraisal and underwriting, with one clear point of contact.
Final terms, the closing table, and a partner to revisit your financing as your plans change.
Pre-approval is not a commitment to lend. Final approval and closing depend on documentation, property review and underwriting.
Planning tools
Model a scenario privately. Nothing you enter here is saved or sent anywhere. Carrying credit card or auto debt? Try the debt consolidation calculator, or see what your home is worth.
Estimated monthly payment
Illustrative interest-only payment
During the first 10 years, including the taxes, insurance and other costs you entered.
Principal is not reduced during the interest-only period, and the payment rises when it ends because the balance is repaid over the remaining term. Assumes a fixed rate for illustration; many interest-only loans are adjustable.
Potential interest savings
By adding $1,000 to principal each month.
Assumes a new, fixed-rate loan and consistent extra principal payments from month one. Taxes, insurance and HOA costs are excluded and continue after loan payoff.
Illustrative first-year payment
Includes the taxes, insurance and other costs you entered.
The note rate does not change. A funded subsidy temporarily offsets payments; borrower qualification generally uses the full note rate. Availability and funding sources vary by program.
Estimates only. Not a Loan Estimate, APR, rate lock, pre-approval or commitment to lend. Excludes closing costs and any financed fees. Actual payments and costs may differ.
Complimentary consultations
For real estate agents
Fast pre-approvals, proactive updates and a loan officer who answers the phone — so your deals close on time. Licensed in Arizona, Florida, Idaho, Nevada, North Carolina, Oregon, Utah and Washington.
Questions
Wondering about something else? There's always room for a conversation.
Ask RickYes. It's an educational class with no cost and no obligation, and you don't need to apply for anything to attend. If you'd like a personal plan afterward, we can set up a one-on-one consultation.
Absolutely. A private consultation starts with your goals, timeline and how your income and assets are held. You don't need documents ready for a first conversation, and nothing is submitted until you choose to apply.
Yes — first-time buyers are a big part of what I do, and I host a free first-time buyer class. We'll walk through budget, credit, down payment and closing costs together, and compare FHA, conventional, VA and down payment assistance options you may be eligible for.
Down payment assistance programs—offered through state housing agencies, local programs and some lenders—can help eligible buyers cover a down payment or closing costs, as a grant or a second loan that may be forgivable or repayable. Eligibility usually depends on income, purchase price, location, credit and sometimes homebuyer education. I can review which programs may fit in the state where you're buying.
Often, yes. The VA Interest Rate Reduction Refinance Loan (IRRRL), also called a VA streamline, refinances your current VA loan into a new one, usually to lower your rate or move from an adjustable to a fixed rate. The VA generally doesn't require a new appraisal, and paperwork is typically lighter than a standard refinance. Eligibility, seasoning and savings requirements apply, and lenders may have their own requirements.
Jumbo loans exceed the conforming loan limit for the property's county. Underwriting is typically more detailed—lenders look closely at down payment, credit, documented income and post-closing reserves. Requirements vary by lender, so comparing across a network can make a real difference.
It depends on how you earn and document it. Options may include traditional tax-return documentation, or alternative-documentation programs such as bank statement loans that look at 12 or 24 months of deposits, or profit-and-loss programs. Qualification and terms vary.
Some programs allow a portion of eligible liquid assets—such as investment or retirement accounts—to be considered when calculating qualifying income. How assets are counted, and which types are eligible, varies by lender and program.
A bank can only offer its own loans. Through Barrett Financial Group, I take your scenario to a wide lender network and place it where it fits best—often valuable when your income, assets or property are less traditional.
I'm licensed in Arizona, Florida, Idaho, Nevada, North Carolina, Oregon, Utah and Washington. You can verify my licenses any time on NMLS Consumer Access.
No. These are planning tools using the assumptions you enter, including a hypothetical rate. They do not check eligibility or pull credit. A personalized quote and any approval require a separate review through the lender's process.
Private consultation
Share a little about what you have in mind. I'll follow up personally to find a time that suits you.
Las Vegas, Nevada
Serving AZ, FL, ID, NV, NC, OR, UT & WA


